


Signup for our email list
Learn about value investing!
(No spam,promise)
promise)
IIM International Portfolios: First Half of 2024
More of the Same – Or Not?
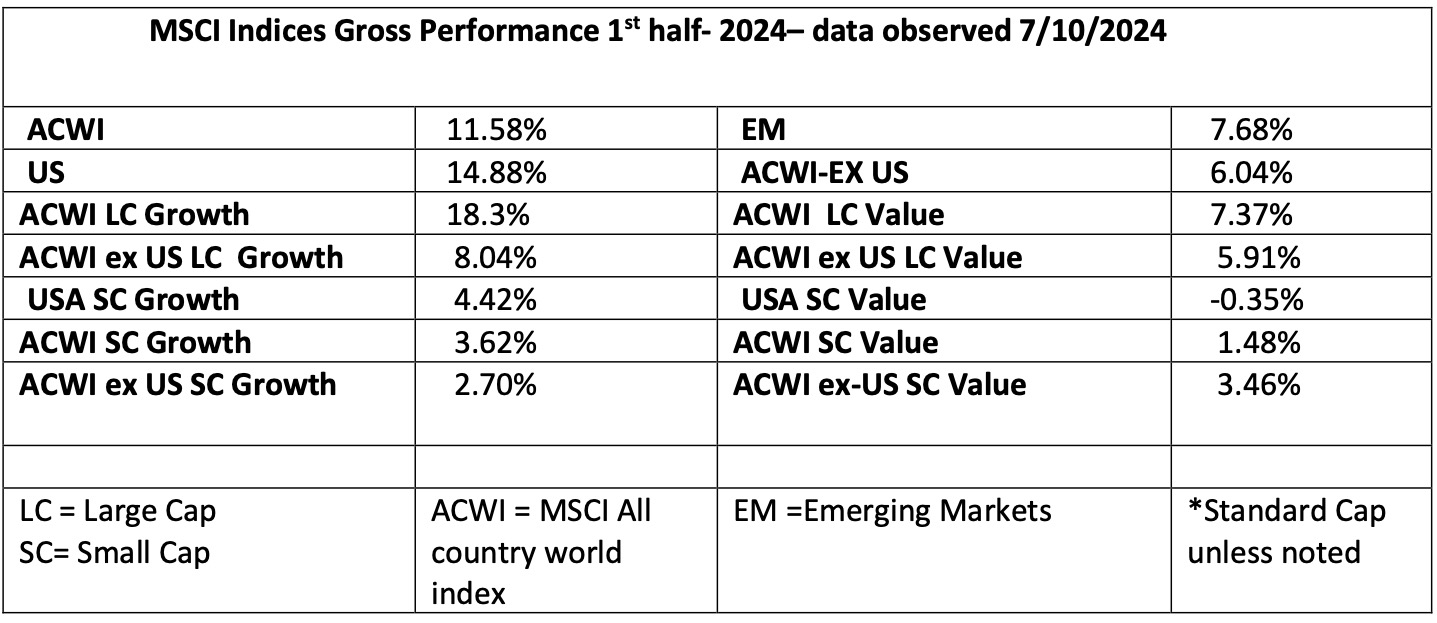
Despite sticky interest rates, wars, saber-rattling and natural disasters, broad US equity indices, and especially growth indices, continued to roll through the 2nd quarter leading to double-digit gains for the first half. These gains according to Morningstar, however, were only possible due to the performance of five major stocks in cap-weighted indices: Nvidia, Apple, Microsoft, Alphabet and Broadcom. Without them, US indices would have been down the second quarter. Indeed, most equal-weighted indices lagged the cap-weighted index by circa 1000 basis points for the full half according to the Wall Street Journal.
Broad, style-neutral, standard international indices showed compelling performance for the first half. Large-cap growth did better than value but not to the extreme as in the US. Small-cap indices underperformed large-cap indices both domestically and abroad. Within this space, growth narrowly outperformed value in the US; this reversed in aggregate internationally.
Other assets yielded mixed returns. With inflation remaining sticky, the Fed did not cut rates as expected at the beginning of the year and investment grade bonds underperformed the S&P 500. On the other hand, SPDR ® Gold Shares returned 12.84% based on NAV and the S&P Cryptocurrency Broad Digital Market Index was up over 35%.
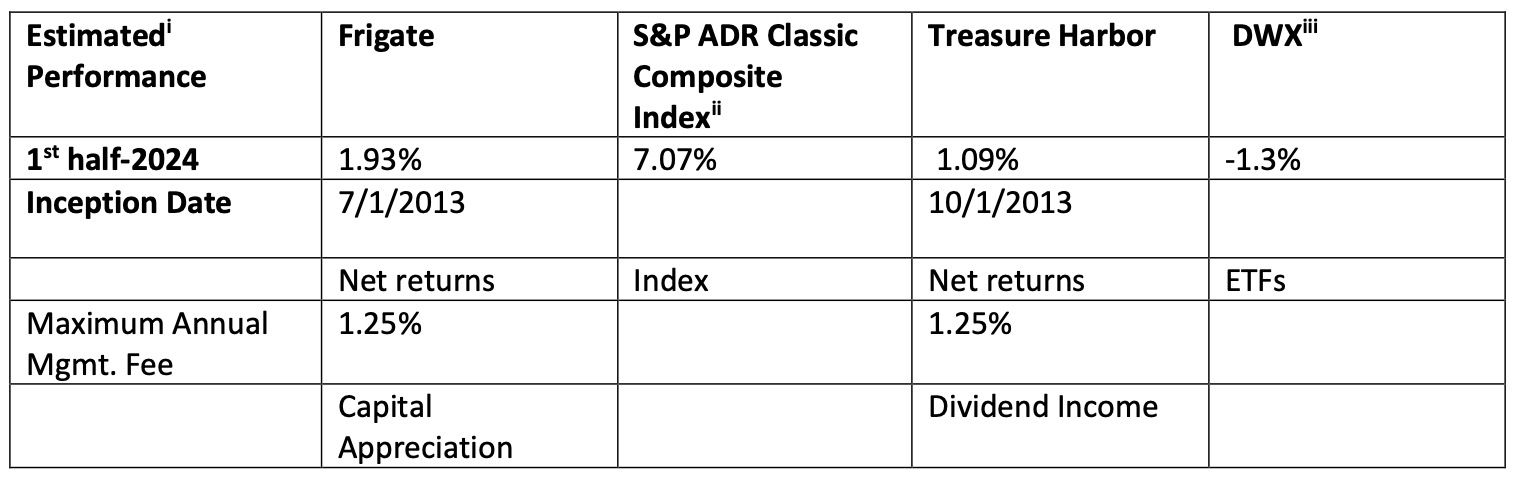
Frigate’s 2nd quarter performance was comparable to its benchmark but year-to-date lagged. Grifols and Adecco continued to lead on the downside for the half year. British fashion house Burberry joined this less than illustrious group as a slowdown in the luxury goods market and higher costs resulted in a severe drop in 2024 reported profits. Not surprising, expected AI demand for semiconductors led to persistent good performance of Taiwan Semiconductor Manufacturing and ASML. Swiss supplier of electrical equipment and automation products ABB became a top performer following fourth quarter reports of strong margins and order trends. Since inception, Folio estimates Frigate’s time-weighted, cumulative, gross returns as 75.75%.
Treasure Harbor continued to outperform is benchmark but experienced a shuffle in poor performers from the first to second quarters of 2024. Brazilian based brewer AMBEV’s local price dropped after first quarter earnings drew concerns on volume growth in major markets, including Canada and Argentina. A deteriorating real further hurt the ADR share price. Telecommunication stocks Rogers Communications of Canada and Spark New Zealand also had significant negative total returns. Semiconductor assembler ASX and financial company Barclays continued their good run through the half; in the meantime, new government property measures helped bolster China Construction Bank (CCB). Since inception, Folio estimates Treasure Harbor’s time-weighted, cumulative gross return, as 57.3%.
Foreign elections kicked off the second half. In France, the New Popular Front, a coalition of left-leading parties, won the most parliamentary seats; unfortunately leaving no single party in control. In the UK, voters replaced Conservative Party PM, Rishi Sunak, with Labour Party leader, Keir Starmer. In Iran, Masoud Pezeshkian beat conservative Saeed Jalili and became the first reformist president in two decades
Investors are factoring also potential outcomes to the US election in their asset allocation. Following the presidential debate, Trump’s strong showing raised the spectre of a one-party government and subsequent inflation. This caused a sell-off in US government bonds. One strategist shared with me that he isn’t concerned over the long-term impact of the election (I may disagree), but suggested keeping some powder dry to take advantage of volatility.
More comprehensively the outlook and recommendation by many strategists are in-line with that following the first quarter. Economic growth in the US has been slowing, it appears that inflation is moderating, there is still hope the Fed will lower rates and a soft landing is expected. With US growth stocks looking expensive, T. Rowe Price suggested in its mid-term report, “2024 Global Market Outlook: Market resilience is uncovering investment opportunities,” that US value and small stocks look attractively valued – the former are a good hedge if interest rates remain high and the latter will show earnings improvement if rates stabilize or decline. They are also recommending adding international stocks, where indices’ have a different industry composition than those in the US, are more value-oriented and may protect against risks in the US market. Thank you, T. Rowe.
As always, please reach out to Cale or myself if you have any questions or suggestions regarding our Spoke Funds ® or your accounts.
Lauretta “Retz” Ann Reeves, CFA AWMA
Footnotes:
(i) Performance figures are estimated and unaudited. Estimated benchmark returns are in the column to the right of its respective Folio. Net Returns are after international taxes on dividends, management fees and trading fees, when necessary. Historical returns are available on request and at Callan and Investment Metrics.
(ii) Gross Return
(iii) SPDR S&P International Dividend ETF. Returns estimated based on NAV.
Disclaimer: This post nor any of the material linked to herein in any way constitutes investment advice. Historical performance data above represents performance results as reported by the portfolio identified. Performance results are for illustration purposes only. Historical results are not indicative of future performance. Positive returns are not guaranteed. Individual results will vary depending on market conditions and timing of initial investment. Investing may cause capital loss. The publication of this performance data is in no way a solicitation or offer to sell securities or investment advisory services.